9 dicembre forconi: Market Crash
Visualizzazione post con etichetta Market Crash. Mostra tutti i post

sabato 1 dicembre 2018

This Is How The "Everything Bubble" Will End

I think there’s a very high chance of a stock market crash of historic proportions before the end of Trump’s first term.
That’s because the Federal Reserve’s current rate-hiking cycle, which started in 2015, is set to pop “the everything bubble.”
I’ll explain how this could all play out in a moment. But first, you need to know how the Fed creates the boom-bust cycle…
To start, the Fed encourages malinvestment by suppressing interest rates lower than their natural levels. This leads companies to invest in plants, equipment, and other capital assets that only appear profitable because borrowing money is cheap.
This, in turn, leads to misallocated capital – and eventually, economic loss when interest rates rise, making previously economic investments uneconomic.
Think of this dynamic like a variable rate mortgage. Artificially low interest rates encourage individual home buyers to take out mortgages. If interest rates stay low, they can make the payments and maintain the illusion of solvency.
But once interest rates rise, the mortgage interest payments adjust higher, making them less and less affordable until, eventually, the borrower defaults.
In short, bubbles are inflated when easy money from low interest rates floods into a certain asset.
Rate hikes do the opposite. They suck money out of the economy and pop the bubbles created from low rates.

It Almost Always Ends in a Crisis

Almost every Fed rate-hiking cycle ends in a crisis. Sometimes it starts abroad, but it always filters back to U.S. markets.
Specifically, 16 of the last 19 times the Fed started a series of interest rate hikes, some sort of crisis that tanked the stock market followed. That’s around 84% of the time.
You can see some of the more prominent examples in the chart below.
Let’s walk through a few of the major crises…
• 1929 Wall Street Crash
Throughout the 1920s, the Federal Reserve’s easy money policies helped create an enormous stock market bubble.
In August 1929, the Fed raised interest rates and effectively ended the easy credit.
Only a few months later, the bubble burst on Black Tuesday. The Dow lost over 12% that day. It was the most devastating stock market crash in the U.S. up to that point. It also signaled the beginning of the Great Depression.
Between 1929 and 1932, the stock market went on to lose 86% of its value.
• 1987 Stock Market Crash
In February 1987, the Fed decided to tighten by withdrawing liquidity from the market. This pushed interest rates up.
They continued to tighten until the “Black Monday” crash in October of that year, when the S&P 500 lost 33% of its value.
At that point, the Fed quickly reversed its course and started easing again. It was the Chairman of the Federal Reserve Alan Greenspan’s first – but not last – bungled attempt to raise interest rates.
• Asia Crisis and LTCM Collapse
A similar pattern played out in the mid-1990s. Emerging markets – which had borrowed from foreigners during a period of relatively low interest rates – found themselves in big trouble once Greenspan’s Fed started to raise rates.
This time, the crisis started in Asia, spread to Russia, and then finally hit the U.S., where markets fell over 20%.
Long-Term Capital Management (LTCM) was a large U.S. hedge fund. It had borrowed heavily to invest in Russia and the affected Asian countries. It soon found itself insolvent. For the Fed, however, its size meant the fund was “too big to fail.” Eventually, LTCM was bailed out.
• Tech Bubble
Greenspan’s next rate-hike cycle helped to puncture the tech bubble (which he’d helped inflate with easy money). After the tech bubble burst, the S&P 500 was cut in half.
• Subprime Meltdown and the 2008 Financial Crisis
The end of the tech bubble caused an economic downturn. Alan Greenspan’s Fed responded by dramatically lowering interest rates. This new, easy money ended up flowing into the housing market.
Then in 2004, the Fed embarked on another rate-hiking cycle. The higher interest rates made it impossible for many Americans to service their mortgage debts. Mortgage debts were widely securitized and sold to large financial institutions.
When the underlying mortgages started to go south, so did these mortgage-backed securities, and so did the financial institutions that held them.
It created a cascading crisis that nearly collapsed the global financial system. The S&P 500 fell by over 56%.
• 2018: The “Everything Bubble”
I think another crisis is imminent…
As you probably know, the Fed responded to the 2008 financial crisis with unprecedented amounts of easy money.
Think of the trillions of dollars in money printing programs – euphemistically called quantitative easing (QE) 1, 2, and 3.
At the same time, the Fed effectively took interest rates to zero, the lowest they’ve been in the entire history of the U.S.
Allegedly, the Fed did this all to save the economy. In reality, it has created enormous and unprecedented economic distortions and misallocations of capital. And it’s all going to be flushed out.
In other words, the Fed’s response to the last crisis sowed the seeds for an even bigger crisis.
The trillions of dollars the Fed “printed” created not just a housing bubble or a tech bubble, but an “everything bubble.”
The Fed took interest rates to zero in 2008. It held them there until December 2015 – nearly seven years.
For perspective, the Fed inflated the housing bubble with about two years of 1% interest rates. So it’s hard to fathom how much it distorted the economy with seven years of 0% interest rates.

The Fed Will Pop This Bubble, Too

Since December 2015, the Fed has been steadily raising rates, roughly 0.25% per quarter.
I think this rate-hike cycle is going to pop the “everything bubble.” And I see multiple warning signs that this pop is imminent.
• Warning Sign No. 1 – Emerging Markets Are Flashing Red
Earlier this year, the Turkish lira lost over 40% of its value. The Argentine peso tanked a similar amount.
These currency crises could foreshadow a coming crisis in the U.S., much in the same way the Asian financial crisis/Russian debt default did in the late 1990s.
• Warning Sign No. 2 – Unsustainable Economic Expansion
Trillions of dollars in easy money have fueled the second-longest economic expansion in U.S. history, as measured by GDP. If it’s sustained until July 2019, it will become the longest in U.S. history.
In other words, by historical standards, the current economic expansion will likely end before the next presidential election.
• Warning Sign No. 3 – The Longest Bull Market Yet
Earlier this year, the U.S. stock market broke the all-time record for the longest bull market in history. The market has been rising for nearly a decade straight without a 20% correction.
Meanwhile, stock market valuations are nearing their highest levels in all of history.
The S&P 500’s CAPE ratio, for example, is now the second-highest it’s ever been. (A high CAPE ratio means stocks are expensive.) The only time it was higher was right before the tech bubble burst.
Every time stock valuations have approached these nosebleed levels, a major crash has followed.

Preparing for the Pop

The U.S. economy and stock market are overdue for a recession and correction by any historical standard, regardless of what the Fed does.
But when you add in the Fed’s current rate-hiking cycle – the same catalyst for previous bubble pops – the likelihood of a stock market crash of historic proportions, before the end of Trump’s first term, is very high.
That’s why investors should prepare now. One way to do that is by shorting the market. That means betting the market will fall.
Keep in mind, I’m not in the habit of making “doomsday” predictions. Simply put, the Fed has warped the economy far more drastically than it did in the 1920s, during the tech or housing bubbles, or during any other period in history.
I expect the resulting stock market crash to be that much bigger.
Authored by Nick Giambruno via InternationalMan.com


The Cracks Appear: A Record $90 Billion A-Rated Bonds Downgraded To BBB In Q4

Having written about it for over a year, it sometimes feels like the topic of "fallen angel" bonds, and the danger they present to the broader credit market and overall economy has been beaten to death (see most recently"The $6.4 Trillion Question: How Many BBB Bonds Are About To Be Downgraded").
But what if the market is focusing on the wrong tier when it comes to the upcoming downgrade deluge? What if instead of BBB credits, whose downgrade risk is, or should be, largely priced in by now (although the recent plunges in GE and PG&E bonds put this assumption to doubt) the real risk is just above the pre-fallen angel tier?
That's the point made by Goldman Sachs overnight, which argues that while some of the "BBB risks" warrant close monitoring, the bank's credit analysts "continue to struggle to see any recent developments that would make BBB-rated bonds a canary in a coal mine." To support their claim that BBB is not the time bomb many others claim it is, Goldman shows that BBB spreads have moved largely in line with their A-rated peers, while demonstrating that BBB bonds have not been an outsized source of weakness in IG.
The bank's assessment is that in the absence of a full-blown recession, downgrade risk among BBB-rated issuers is likely to remain  contained to structurally and cyclically challenged sectors and firms. As a result, Goldman's credit analysts view the risks as most pronounced in sectors including Food and Beverage, Retail/Consumer, and Autos. Meanwhile, they see value in other BBB-heavy  sectors such as Banks and Telecom.
In any case, the bottom line is that according to Goldman at least, investors should not be worried about BBB (that said, on Nov 1 Goldman told clients to buy oil; what followed next was the worst month for oil in 10 years).
So if not BBB, then where is the biggest credit risk in the investment grade space?
According to Goldman, the more pronounced risk facing IG investors, is a wave of downgrades among firms rated A and AA.
In our view, these companies are more likely to use their debt capacity for shareholder returns and/or M&A to diversify their businesses. In contrast, firms at the cusp of HY ratings should be inclined to manage their balance sheets more conservatively.
Is Goldman right this time? Who knows, but recent rating actions suggest that the bank may have a point: in the fourth quarter alone, a record $90 billion worth of "pre-fallen angel" were downgraded to BBB from A, and Goldman adds that the risk "remains skewed towards further negative actions."
But while rating agencies are clearly adding to the pre-fallen angel camp, there is no denying that the big threat is what happens if and when the BBB downgrade deluge begins. As Deutsche Bank calculated last week, when looking at those bonds most at risk of getting junked, $150bn of the $736bn of BBB- bonds are currently on negative watch/outlook with at least one rating agency, and in danger of imminent "junking."
And while Goldman remains clearly complacent about the BBB space at least until a recession hits, as Deutsche Bank warned last week, even before we get to an economic slowdown - some time in 2020 - or even before the market start pricing the slowdown in, "it feels like the tide might be turning and we start to see fallen angels outpace rising stars over the next year."

So there you have it: for those who believe a recession is either imminent or will soon be priced in, keep shorting the BBB space. Meanwhile, those who think it will take some more time before the rating agencies filter out the noise, the best place to be short is those "pre-fallen" A bonds who will first become BBBs, before they too join the deluge into the junk space some time around late 2019/early 2020.
Fonte: qui

domenica 11 novembre 2018

The "Nightmare Scenario" For Beijing: 50 Million Chinese Apartments Are Empty

Back in 2017, we explained why the "fate of the world economy is in the hands of China's housing bubble." The answer was simple: for the Chinese population, and growing middle class, to keep spending vibrant and borrowing elevated, it had to feel comfortable and confident that its wealth would keep rising. However, unlike the US where the stock market is the ultimate barometer of the confidence boosting "wealth effect", in China it has always been about housing as three quarters of Chinese household assets are parked in real estate, compared to only 28% in the US, with the remainder invested financial assets.

Source: Xinhua

Beijing knows this, of course, which is why China periodically and consistently reflates its housing bubble, hoping that the popping of the bubble, which happened in late 2011 and again in 2014, will be a controlled, "smooth landing" process.  For now, Beijing has been successful in maintaining price stability at least according to official data, allowing the air out of the "Tier 1" home price bubble which peaked in early 2016, while preserving modest home price appreciation in secondary markets.
How long China will be able to avoid a sharp price decline remains to be seen, but in the meantime another problem faces China's housing market: in addition to being the primary source of household net worth - and therefore stable and growing consumption - it has also been a key driver behind China's economic growth, with infrastructure spending and capital investment long among the biggest components of the country's goalseeked GDP. One result has been China's infamous ghost cities, built only for the sake of Keynesian spending to hit a predetermined GDP number that would make Beijing happy.
Meanwhile, in the process of reflating the latest housing bubble, another dire byproduct of this artificial housing "market" has emerged: tens of millions of apartments and houses standing empty across the country.
According to Bloomberg, soon-to-be-published research will show that roughly 22% of China’s urban housing stock is unoccupied, according to Professor Gan Li, who runs the main nationwide study. That amounts to more than 50 million empty homes.
The reason for the massive empty inventory glut: to keep supply low and prices artificially elevated by taking out as much inventory off the market as possible. This, however, works both ways, and while it helps boost prices on the way up as the economy grow and speculators flood the housing market with easy money, the moment the trend flips the spike in supply as empty units are offloaded will lead to a panic liquidation of homes, resulting in what may be the biggest housing market crash ever observed, and putting the US home bubble of 2006 to shame.
Indeed, as Bloomberg notes, the "nightmare scenario" for Chinese authorities is that owners of unoccupied dwellings rush to sell when cracks start appearing in the property market, causing a self-reinforcing downward price spiral.
Worse, the latest data, from a survey in 2017, also suggests Beijing’s efforts to curb property speculation - which alongside shadow banking and the persistent threat of sudden bank runs (like the one discussed last week) is considered by Beijing a key threat to financial and social stability - have failed.
"There’s no other single country with such a high vacancy rate,” said Gan, of Chengdu’s Southwestern University of Finance and Economics. “Should any crack emerge in the property market, the homes to be offloaded will hit China like a flood.”
How did the Chinese researcher obtain this troubling number? To find the percentage of vacant housing, thousands of researchers spread out across 363 Chinese counties last year as part of the China Household Finance Survey, which Gan runs at the university.
Gan said that the vacancy rate, which excludes homes yet to be sold by developers, was little changed from a 2013 reading of 22.4%. And while that study showed 49 million vacant homes, Gan puts the number now at "definitely more than 50 million units."
Meanwhile, Beijing - which is fully aware of these stats, and is also aware that even a modest price decline could be magnified instantly as millions of "for sale" units hit the market at the same time - is worried. That's why Chinese authorities have imposed buying restrictions and limited credit availability, only to see money flooding into other areas. Rampant price gains also mean millions of people are shut out from the market, exacerbating inequality.
In fact, China's president Xi famously said in October last year that "houses are built to be inhabited, not for speculation", and yet a quarter of China's housing is just that: empty, and only serves to amplify speculation.
While holiday homes and the empty dwellings of migrants seeking work elsewhere account for some of the deserted properties, Gan found that investment purchases have been the biggest factor keeping the vacancy rate high. That’s despite curbs across the country meant to discourage buying of multiple dwellings.
There is another economic cost to this speculative frenzy: the drop in supply puts upward pressure on prices and crowds young buyers out of the market, according to Kaiji Chen, who co-authored a Fed paper called “The Great Housing Boom of China." 
And, as Americans so fondly recall, the result of chasing unaffordable homes for the purpose of price speculation has resulted in yet another unprecedented debt bubble: according to Caixin, outstanding personal home mortgages in China have exploded sevenfold from 3 trillion yuan ($430 billion) in 2008 to 22.9 trillion yuan in 2017, according to PBOC data
By the end of September, the value of outstanding home mortgages had surged another 18% Y/Y to a record 24.9 trillion yuan, resulting in a trend that as Caixin notes, has turned many people into what are called “mortgage slaves."
It has also resulted in yet another housing bubble: home mortgage debt now makes up more than half of total household debt in China. As of the third quarter, it accounted for 53% of the 46.2 trillion yuan in outstanding household debt.
For now, few are losing sleep over what will be the next massive housing bubble to burst. An example of a vacant home is a villa on the outskirts of Shanghai that 27-year-old Natalie Feng’s parents bought for her. The two-story residence was meant to be a weekend escape for the family of three. In reality, it’s empty most of the time, and Feng says it’s too much trouble to rent it out.
"For every weekend we spend there, we need to drive for an hour first, and clean up for half a day," Feng said. She joked that she sometimes wishes her parents hadn’t bought it for her in the first place. That’s because any apartment she buys now would count as a second home, which means she’d have to make a bigger down payment.
* * *
What is troubling is that despite relatively stable home prices, the foundations behind the housing market are cracking. As the WSJ recently reported, in early December, a group of homeowners stormed the sales office of their Shanghai complex, "Central Washington", whose developer, Shanghai Zhaoping Real Estate Development, was advertising new apartments at a fraction of the prices of the ones sold earlier in the year. One apartment owner said the new prices suggested the value of the apartment she bought from the developer in March had dropped by about 17.5%.
“There are people who bought multiple homes who are now trying to sell one to pay off the mortgage on another,” said Ran Yunjie, a property agent. One of his clients bought an apartment last year for about $230,000. To find a buyer now, the client would have to drop the price by 60%, according to Ran.
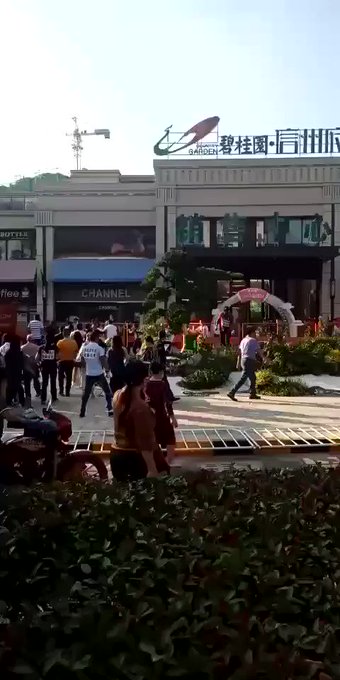
Meanwhile, in a truly concerning demonstration of what will happen when the bubble finally bursts, last month we reported that angry homeowners who paid full price for units at the Xinzhou Mansion residential project in Shangrao attacked the Country Garden sales office in eastern Jiangxi province last week, after finding out it had offered discounts to new buyers of up to 30%.


Country Garden cut the selling price at one of its residential developments by 1/3. Those who paid full price smashed the sales office. Similar incidents had happened before, and will again. It’s impossible to remove “the guarantee of principal”(刚性兑付)in China.

265 people are talking about this
"Property accounts for roughly 70 per cent of urban Chinese families’ total assets – a home is both wealth and status. People don’t want prices to increase too fast, but they don’t want them to fall too quickly either,” said Shao Yu, chief economist at Oriental Securities. "People are so used to rising prices that it never occurred to them that they can fall too. We shouldn’t add to this illusion," Shao added, echoing Ben Bernanke circa 2005.
But the biggest surprise once the music finally stops may be that - as a fascinating WSJ report revealed one year ago - China's housing downturn is likely far, far worse than meets the eye, as under Beijing’s direction more than 200 cities across China for the last three years have been buying surplus apartments from property developers and moving in families from condemned city blocks and nearby villages. China’s Housing Ministry, which is behind the purchases, said it plans to continue the program through 2020. The strategy, supported by central-government bank lending, has rescued housing developers and lifted the property market.
In other words, while China already has a record 50 million empty apartments, the real number - when excluding the government's own stealthy purchases of excess inventory - is likely significantly higher. It is this, and not China's stock market, that has long been the biggest time bomb for Beijing, and if Trump and Peter Navarro truly want to crush China in their ongoing trade war, they should focus on destabilizing the housing market: the Chinese stock market was, and remains just a distraction.
To summarize:
  • China has more than 50 million vacant apartments
  • Mortgage loans have grown 8-fold in the past decade
  • Prices are kept steady thanks to constant government purchases of surplus inventory
  • Home prices are already cracking, with some homebuilders forced to cut prices by 30%.
  • Homebuyers revolt, forming angry militias and storm homesellers' offices when prices dip
For now, China has been able to maintain the illusion of stability to preserve social order. However, should the housing slowdown accelerate significantly and tens of millions in empty units suddenly hit the market, then the "working class insurrection" that China has been preparing for since 2014...

... will become an overnight reality, with dire consequences for the entire world.
Fonte: qui

"A Chinese Recession Is Inevitable" 

Ken Rogoff Ruins 'Decoupled-America' Narrative


Analysts say a Chinese recession would only hurt the region. That may be wishful thinking...
When China finally has its inevitable growth recession – which will almost surely be amplified by a financial crisis, given the economy’s massive leverage – how will the rest of world be affected? With US President Donald Trump’s trade war hitting China just as growth was already slowing, this is no idle question.
Typical estimates, for example those embodied in the International Monetary Fund’s assessments of country risk, suggest an economic slowdown in China will hurt everyone. But the acute pain, according to the IMF, will be more regionally concentrated and confined than would be the case for a deep recession in the United States.
Unfortunately, this might be wishful thinking.
First, the effect on international capital markets could be vastly greater than Chinese capital market linkages would suggest. However jittery global investors may be about prospects for profit growth, a hit to Chinese growth would make things a lot worse. Although it is true that the US is still by far the biggest importer of final consumption goods (a large share of Chinese manufacturing imports are intermediate goods that end up being embodied in exports to the US and Europe), foreign firms nonetheless still enjoy huge profits on sales in China.
Investors today are also concerned about rising interest rates, which not only put a damper on consumption and investment, but also reduce the market value of companies (particularly tech firms) whose valuations depend heavily on profit growth far in the future. A Chinese recession could again make the situation worse.
I appreciate the usual Keynesian thinking that if any economy anywhere slows, this lowers world aggregate demand, and therefore puts downward pressure on global interest rates. But modern thinking is more nuanced. High Asian saving rates over the past two decades have been a significant factor in the low overall level of real (inflation-adjusted) interest rates in both the US and Europe, thanks to the fact that underdeveloped Asian capital markets simply cannot constructively absorb the surplus savings.
Former US Federal Reserve chair Ben Bernanke famously characterised this much-studied phenomenon as a key component of the “global savings glut”. Thus, instead of leading to lower global real interest rates, a Chinese slowdown that spreads across Asia could paradoxically lead to higher interest rates elsewhere – especially if a second Asian financial crisis leads to a sharp draw-down of central bank reserves. Thus, for global capital markets, a Chinese recession could easily prove to be a double whammy.
As bad as a slowdown in exports to China would be for many countries, a significant rise in global interest rates would be much worse. Eurozone leaders, particularly German Chancellor Angela Merkel, get less credit than they deserve for holding together the politically and economically fragile single currency against steep economic and political odds. But their task would have been well-nigh impossible but for the ultra-low global interest rates that have allowed politically paralysed eurozone officials to skirt needed debt write-downs and restructurings in the periphery.
When the advanced countries had their financial crisis a decade ago, emerging markets recovered relatively quickly, thanks to low debt levels and strong commodity prices. Today, however, debt levels have risen significantly, and a sharp rise in global real interest rates would almost certainly extend today’s brewing crises beyond the handful of countries (including Argentina and Turkey) that have already been hit.
Nor is the US immune. For the moment, the US can finance its trillion-dollar deficits at relatively low cost. But the relatively short-term duration of its borrowing – under four years if one integrates the Treasury and Federal Reserve balance sheets – means that a rise in interest rates would soon cause debt service to crowd out needed expenditures in other areas. At the same time, Trump’s trade war also threatens to undermine the US economy’s dynamism. Its somewhat arbitrary and politically driven nature makes it at least as harmful to US growth as the regulations Trump has so proudly eliminated. Those who assumed that Trump’s stance on trade was mostly campaign bluster should be worried.
The good news is that trade negotiations often seem intractable until the 11th hour. The US and China could reach an agreement before Trump’s punitive tariffs go into effect on 1 January. Such an agreement, one hopes, would reflect a maturing of China’s attitude toward intellectual property rights – akin to what occurred in the US during the late 19th century. (In America’s high growth years, US entrepreneurs often thought little of pilfering patented inventions from the United Kingdom.)
A recession in China, amplified by a financial crisis, would constitute the third leg of the debt super-cycle that began in the US in 2008 and moved to Europe in 2010. Up to this point, the Chinese authorities have done a remarkable job in postponing the inevitable slowdown. Unfortunately, when the downturn arrives, the world is likely to discover that China’s economy matters even more than most people thought.
Authored by Kenneth Rogoff, op-ed via The Guardian